A foreign vacation with your spouse sounds wonderful — until you realise the trip you’re imagining costs ₹5 lakh, and your current plan is “we’ll figure it out closer to the date.” That approach leads to either a downgraded trip or a credit card bill that haunts you for the next year. Saving for foreign vacation is not complicated, but it does require a number, a timeline, and a monthly commitment — starting now. This article gives salaried Indians, beginners, and families a clear 24-month plan: how much to save, where to keep it, what risks to watch, and what mistakes to avoid. No product recommendations. Just a practical framework you can start this weekend.
Quick Answer: Saving for Foreign Vacation
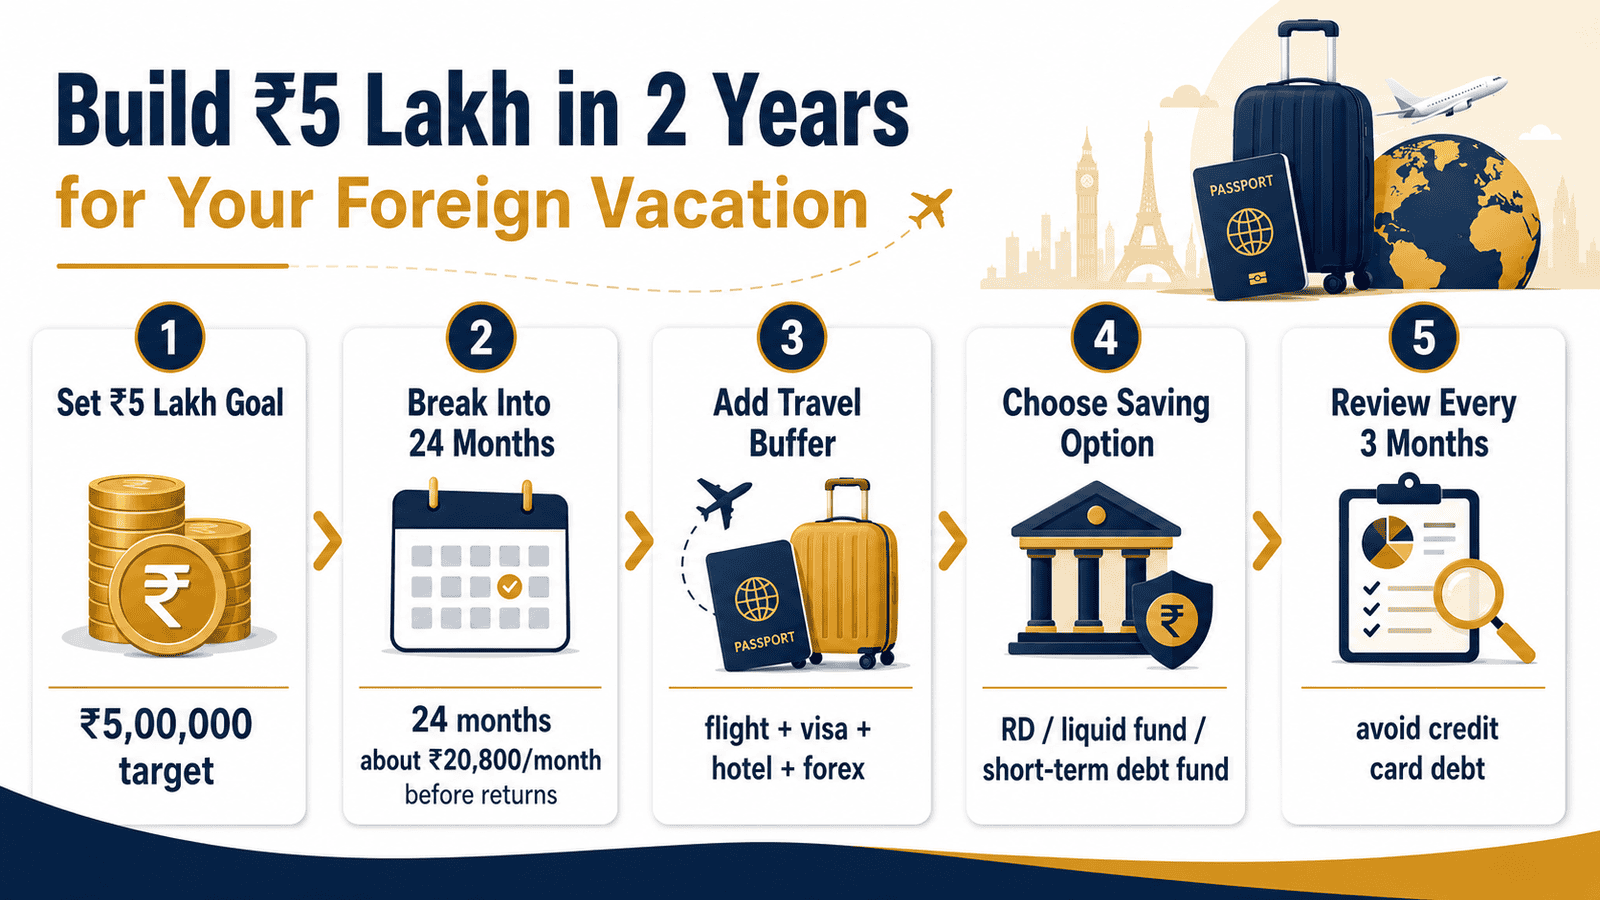
Saving for foreign vacation needs a clear target, separate account, and monthly plan. To build ₹5 lakh in 2 years, you need about ₹20,800 per month before returns. Use low-risk options for short-term goals, add a travel buffer, and avoid funding the trip through credit card debt.
Key Takeaways
- ₹5 lakh over 24 months requires approximately ₹20,833 per month before any investment returns — round up to ₹21,000 for a safety buffer.
- Build a 10–15% travel buffer above the visible package cost to cover forex markup, visa fees, travel insurance, local transport, and price changes.
- For a fixed 2-year goal, capital safety and liquidity matter more than chasing higher returns — use lower-risk, liquid options, not equity funds.
- Your emergency fund must be fully in place before you direct ₹21,000 a month toward a discretionary travel goal.
- Avoid revolving credit card balances to pay for the trip — interest at 36–42% per annum wipes out any travel rewards benefit.
- A separate, named goal account reduces the risk of accidentally spending your vacation corpus on everyday expenses.
Key Facts at a Glance
| Parameter | Detail | Note |
|---|---|---|
| Goal amount | ₹5,00,000 | All-in budget including buffer |
| Timeline | 24 months | Fixed, non-negotiable deadline |
| Monthly saving needed | ~₹20,833 (round to ₹21,000) | Before any investment return |
| Suitable options | Savings account, RD, short-term FD, liquid fund, short-duration debt fund | Based on risk comfort and liquidity need |
| Avoid | Equity funds, crypto, stock tips, personal loan, credit card rollover | Too volatile or too costly for a 2-year fixed goal |
| Buffer range | 10–15% above visible trip cost | For forex, visa, insurance, emergencies |
Product returns and current bank rates must be verified with provider data before publishing. Refer to RBI (rbi.org.in) and SEBI (sebi.gov.in) for regulatory guidance.
How to Turn a Foreign Vacation Dream into a Saving for Foreign Vacation Plan
Step 1: Define the goal before you open any account
Most people skip straight to “which mutual fund should I use?” without first nailing down the actual number. Before you touch a single product, answer four questions: Which destination? How many travellers? Which month are you travelling? What is the total all-in budget?
A ₹5 lakh target for two people on an international trip to Southeast Asia or Europe is realistic for a mid-range experience. Break it down — flights (~₹80,000–₹1,20,000 for two), accommodation (~₹60,000–₹80,000), visa fees (~₹8,000–₹20,000 depending on destination), travel insurance (~₹3,000–₹8,000), forex cash and card expenses, food, local transport, activities, and shopping. Add a 10–15% buffer for price changes and unexpected costs. That buffer is not optional — it is what separates a comfortable trip from a stressful one.
Step 2: Open a separate goal account
The single most underrated tool in vacation planning is a dedicated, separate savings account or instrument labelled specifically for this goal. When your travel corpus sits in your regular salary account, it gets spent on groceries, OTT subscriptions, and impulsive weekend dinners. A separate account makes the money feel off-limits. Name it “Foreign Trip — Dec 2026” on your banking app if the option exists. That psychological friction alone prevents casual dipping. Before you set up this account, check that you have a working monthly budget — understanding how to create a monthly budget for salaried Indians will show you exactly where the ₹21,000 monthly saving will come from.
Step 3: Understand why returns are secondary here
For a 2-year goal with a fixed deadline, the priority order is: capital safety first, liquidity second, returns third. This is the opposite of long-term investing. If you put ₹5 lakh into an equity mutual fund and the market drops 20% in month 22, you are either taking a loss or postponing the trip. Neither is acceptable for a goal you have planned around a specific date.
According to SEBI guidelines, mutual fund investments in equity schemes are subject to market risks and are generally suitable for longer time horizons. Short-term debt and liquid funds carry lower but non-zero risk — interest rate movements and credit events can affect NAV. A savings account or RD carries the lowest product-level risk for a fixed-timeline goal, even if the return is lower.
Step 4: Automate and do not touch it
Set up an auto-transfer on the day after salary credit. This removes the decision fatigue of manually moving money every month. If the saving runs on autopilot for 24 months, you arrive at the goal without drama. If you rely on willpower alone, at least 3–4 months of contributions will get diverted to something else.
Real Example: Ananya and Karan’s European Trip Fund
Ananya (32) and Karan (34), Pune, work in tech and finance respectively. Their combined monthly take-home is ₹1.8 lakh. They want to travel to Europe for two weeks in December 2026 — roughly 24 months away. Their all-in budget estimate is ₹5 lakh for two, including flights, accommodation, visa, insurance, forex, food, activities, and a buffer.
They decide to save ₹21,000 per month starting immediately. Karan sets up an auto-transfer to a separate savings account the day after salary credit. They keep ₹15,000 in a savings account for the first 12 months (high liquidity, in case the trip date shifts). The remaining ₹6,000 per month goes into an RD for slightly better structure and discipline. In month 13, once they have confirmed their travel dates and are confident about the destination, they review whether any portion can stay in a liquid fund for marginally better returns — with the understanding that the money must be out and available 2–3 months before travel.
They also budget ₹60,000 as a buffer — specifically for last-minute exchange rate changes, visa appointment fees, and travel insurance. This is an illustration only, not personalised advice. Actual travel costs, visa fees, forex rates, and insurance premiums vary and must be verified before planning.
How to Calculate Your Monthly Saving Target
Monthly saving needed = Goal Amount ÷ Number of Months
₹5,00,000 ÷ 24 = ₹20,833 per month
Round up to ₹21,000 per month. That extra ₹167 per month compounds the discipline habit and adds ~₹4,000 to your corpus over 24 months — effectively part of your buffer.
If you use a goal-based SIP or RD that earns an illustrative return, the required monthly contribution comes down slightly. The table below shows the impact of different return assumptions on the monthly amount you need to set aside:
| Assumed Illustrative Return | Approx. Monthly Saving Needed | Notes |
|---|---|---|
| 0% (pure saving) | ₹20,833 | Baseline — savings account with no meaningful return |
| 4% p.a. (illustrative) | ~₹20,000 | Roughly aligned with some RD/savings products — verify current rates |
| 6% p.a. (illustrative) | ~₹19,200 | Possible with some liquid or debt fund options — market-linked, not guaranteed |
Important: A higher assumed return should never be an excuse to save less. If the market-linked instrument underperforms or there is a redemption delay, you fall short of your goal. Always base your commitment on the 0% scenario and treat any return as a bonus. To understand whether a SIP structure suits your goal, read about how SIP works and use the SIP calculator to model your monthly contribution. Mutual fund investments are subject to market risks — read all scheme-related documents carefully before investing.
Comparison: Savings Options for a 2-Year Vacation Goal
| Option | Key Characteristic | Best For |
|---|---|---|
| Savings account | Highest liquidity; lower return; capital fully safe; instant access | First layer — always accessible if travel plans change |
| Recurring Deposit (RD) | Monthly discipline enforced; predictable structure; rates vary by bank — verify before opening; premature closure may attract penalty | Readers who want forced discipline with a fixed monthly amount |
| Fixed Deposit (FD) | Useful for a lump sum already in hand; premature withdrawal rules and penalties vary by bank — verify; rates must be checked currently | Parking a windfall (bonus, arrears) toward the goal |
| Liquid mutual fund | Market-linked NAV; generally very short duration; not risk-free; redemption usually T+1 to T+2 business days; returns not guaranteed | Readers comfortable with low but non-zero market risk |
| Short-duration debt fund | Slightly higher duration risk and credit risk than liquid fund; NAV can move with rate changes; not suitable for very risk-averse readers | Only if reader understands interest-rate and credit risk |
For a detailed comparison of monthly saving products, see FD vs RD — which is better for monthly savings. None of the options above is universally “best” — the right choice depends on your risk tolerance, flexibility need, and whether the travel date is fixed.
How to Decide What’s Right for You
Your travel date is fixed and you cannot afford to fall short — THEN use savings account or RD for the full corpus. Certainty beats a marginally higher return.
You are comfortable with low market-linked risk and understand that NAV can move — THEN a portion in a liquid fund is acceptable for the second half of the saving window, not the first.
You receive a bonus or annual incentive during the 24 months — THEN park it in an FD or RD earmarked for the trip immediately; do not let it sit in your salary account.
Your income is irregular or you have variable monthly take-home — THEN extend the timeline to 30–36 months or reduce the destination budget before starting; do not start and stop saving irregularly.
You have not yet built a 3–6 month emergency fund — THEN build that first. Use the emergency fund calculator to check your target before directing ₹21,000 a month toward a discretionary goal.
You have high-interest debt (credit card rollover, personal loan above 15% p.a.) — THEN this saving plan should wait. Paying off that debt first saves more money than any investment return from a vacation corpus.
Common Mistakes to Avoid
Starting with destination photos instead of a total budget
Browsing Instagram reels of Santorini or Bali before you have a number leads to unrealistic planning.
Most people dramatically underestimate total trip cost by ignoring visa fees, forex conversion losses, travel insurance, local transport, and last-minute purchases — which easily add 20–30% above the visible package cost.
Build the full budget spreadsheet first. Then browse the photos.
Ignoring forex markup and card surcharges
Your travel spend is in foreign currency. A 3–4% forex markup on every international card transaction is invisible at the point of swipe but significant across 10–15 days of spending.
On ₹1.5 lakh of international card spend, a 3.5% markup costs you ₹5,250 extra. Multiply that across cash withdrawals and hotel blocks and the leakage is real.
Factor forex costs explicitly into your ₹5 lakh budget — do not treat them as a rounding error.
Using equity funds or stocks for a 2-year fixed goal
Equity markets can fall 20–30% in a 6–12 month period and take 2–3 years to recover.
If you invest ₹5 lakh in an equity fund and it is worth ₹3.9 lakh when your flight departs, you have a painful choice: sell at a loss or cancel the trip. Neither is acceptable for a discretionary goal with a hard deadline.
Use equity only for goals 5+ years away. Keep the vacation corpus in capital-safe, liquid instruments.
Depending on credit card EMI or minimum amount due after the trip
Paying the minimum amount due on a credit card at 36–42% effective annual interest turns a ₹5 lakh trip into a ₹7–8 lakh liability over 18–24 months of repayment.
Travel rewards and air miles do not offset interest at these rates. If you cannot pay the full bill on due date, the trip is not yet affordable.
Build the corpus before you travel — not a repayment plan after.
Increasing lifestyle expenses while saving
Many households start a vacation saving plan but simultaneously upgrade their car, increase dining-out frequency, or subscribe to new streaming services.
Lifestyle inflation quietly erodes the ₹21,000 saving discipline. Keep your monthly expenses stable for 24 months — every rupee of lifestyle creep is a rupee stolen from your trip. Read about how lifestyle inflation works and how to control it to protect your saving streak.
Waiting for “the right time” to start
Every month of delay increases the monthly saving needed. Waiting 3 months means you now need ₹23,800 per month for a 21-month window — ₹3,000 more per month.
The best time to start is today. The second best time is tomorrow morning with an auto-transfer set up.
When This May Not Be the Right Choice
A ₹5 lakh foreign vacation goal is a discretionary target — it should not come at the cost of your financial stability. Consider postponing or scaling down if:
You have no emergency fund or high-interest debt. Directing ₹21,000 per month to a vacation account while carrying a personal loan at 16–18% or a credit card rollover at 36% p.a. makes no financial sense.
Your job or income is genuinely uncertain. If there is a real risk of income disruption in the next 12–18 months, a fixed ₹21,000 monthly commitment could become a source of stress rather than joy.
Major family expenses are due in the same window. School admissions, a home down payment, a medical procedure, or an upcoming childbirth all take priority over a leisure trip. Competing goals in the same 24 months lead to all of them being underfunded.
Saving ₹21,000 monthly would cut into essential insurance premiums or necessities. If contributing this amount forces you to reduce health insurance cover or skip term insurance premiums, the math does not work.
If any of these apply to your situation, it may be worth exploring alternatives before committing.
Official Rules and Where to Verify
This topic involves banking products, mutual funds, travel insurance, and potential tax implications. Before making any financial decision, verify current figures and rules from the following official sources:
- RBI (rbi.org.in) — for savings account and RD/FD regulatory guidance, bank-related rules, and foreign exchange norms for travellers
- SEBI (sebi.gov.in) — for mutual fund regulation, including liquid fund and debt fund risk classifications and NAV-related rules
- IRDAI (irdai.gov.in) — for travel insurance product regulation, claim processes, and insurer verification
- Income Tax Department (incometax.gov.in) — for tax treatment of interest income from RD/FD or capital gains from debt fund redemptions, which may apply depending on your tax bracket and holding period
Rules, limits, and rates on this topic can change with each Budget or regulatory update. Always verify current figures directly from the official source before making any financial decision.
Expert Tips
- Name the account explicitly. Label your goal account “Foreign Trip — Dec 2026” on your banking app. A named account creates psychological ownership — you are far less likely to dip into it for casual expenses than you would a generic savings account.
- Automate the transfer the day after salary credit. Set a standing instruction so the ₹21,000 moves before you see the balance. Saving is a system, not a decision — remove the decision.
- Keep a 10–15% cost buffer above the visible package price. If your travel agent quotes ₹4.2 lakh for flights and hotels, your actual budget should be ₹4.8–₹5 lakh. Forex markups, visa appointment fees, travel insurance, and airport expenses routinely consume this buffer. Verify current cost assumptions before finalising your target.
- Review flight prices and exchange rates quarterly, not daily. Checking every day is anxiety-inducing and does not help. A quarterly check is enough to course-correct if your target needs adjusting.
- Use an expected bonus to reduce monthly pressure — not to delay saving. If you get a performance bonus in month 6 or 12, park it directly in the travel goal account. Do not use it as a reason to skip monthly contributions.
- Reduce the destination budget before you consider debt. If costs rise or saving falls short, the first lever is a more affordable destination or shorter trip — not a personal loan or credit card EMI. The trip should fit the corpus, not the other way around.
- Plan redemption timing carefully for market-linked instruments. If any part of your vacation corpus is in a liquid or debt fund, redeem it 4–6 weeks before you need the forex or make bookings — allow for T+1 or T+2 settlement and any market movement buffer.
Frequently Asked Questions
How much should I save monthly for ₹5 lakh in 2 years?
Without any investment return, you need ₹20,833 per month — round this to ₹21,000. If your saving vehicle earns a return, the required monthly amount reduces slightly, but always base your commitment on the no-return scenario and treat any earnings as a bonus. Use the SIP calculator to model different return assumptions.
Is SIP a good option for a foreign vacation goal?
An SIP into an equity fund is not suitable for a fixed 2-year deadline — equity markets can fall significantly in the short term, and you may need to redeem at a loss. If you use an SIP into a liquid or short-duration debt fund, the risk is lower but still market-linked. According to SEBI regulations, mutual fund investments are subject to market risks. Read all scheme documents carefully. Capital safety and liquidity should be the priority for a goal with a hard deadline.
Is RD better than SIP for a 2-year trip?
For most salaried readers who want certainty — yes, an RD offers more predictable outcomes for a fixed-timeline goal. The return may be lower than a debt fund SIP in a favourable rate environment, but you know exactly what you will have at maturity. Premature withdrawal penalties and current RD rates vary by bank — verify before opening. For a detailed comparison, see FD vs RD — which is better for monthly savings.
Should I use credit card reward points for a foreign vacation?
Using reward points for flight or hotel redemption is sensible — if you are paying your bill in full every month. The moment you carry a revolving balance, the interest at 36–42% per annum completely negates any rewards earned. Never treat credit card reward points as a savings strategy for a ₹5 lakh trip.
How much buffer should I keep for forex and visa costs?
A 10–15% buffer above your visible trip cost is a reasonable planning assumption. This covers forex conversion costs (typically 3–5% on international card transactions depending on the card and bank), visa application fees, travel insurance premium, airport meals and transport, and last-minute price changes. Verify current forex markup rates and visa fee structures before finalising your target, as these change.
Can I use a liquid fund for travel savings?
Yes, but with clear awareness of the risks. Liquid funds are market-linked — their NAV can move, and returns are not guaranteed. They are generally considered lower-risk than equity funds but are not equivalent to a savings account. Redemption typically takes T+1 to T+2 business days. If you use a liquid fund for part of your corpus, plan to redeem 4–6 weeks before you need the money. SEBI regulates liquid funds under its mutual fund framework — read the scheme information document before investing.
What if my travel costs rise before the trip?
This is exactly what your 10–15% buffer is for. If costs rise beyond that, your first option is to adjust the destination or trip duration — not to take a personal loan. If you have been saving ₹21,000 consistently, you will have the flexibility to course-correct. Review your budget at the 12-month mark to confirm whether the corpus is on track relative to current flight and accommodation prices.
Can I use my emergency fund for the vacation if the corpus falls short?
No. An emergency fund is not a backup vacation account. It exists to protect you from income disruption, medical emergencies, or sudden expenses — events that can happen at any time, including during or right after the trip. Depleting the emergency fund for a discretionary vacation leaves you financially exposed. If the corpus falls short, adjust the trip, not the safety net.
Final Verdict
Saving for foreign vacation is entirely realistic for a salaried Indian household — provided the goal has a number, a timeline, and a monthly commitment behind it. ₹5 lakh in 24 months means roughly ₹21,000 per month, saved consistently in a separate account, using lower-risk and liquid options that keep your capital safe and accessible. Returns are a bonus, not the plan. A 10–15% travel buffer separates a stress-free trip from a financially painful one. Your emergency fund must remain intact, and high-interest debt should be cleared before a discretionary saving goal gets its share of your income. Use a goal-based planner, automate the transfer, and review costs quarterly. Plan the trip like a goal, not like an impulse purchase. Always verify the latest rules from official sources or consult a qualified professional before making any financial decision.
This article is for educational purposes only and should not be treated as personalised financial, tax, investment, insurance, or legal advice. Tax rules, interest rates, regulatory limits, and product features can change with each Budget or policy update. Please verify current rules from official government sources or consult a qualified and registered professional before making any financial decision.
Ishita Sharma writes about goal-based financial planning for Indian families and individuals. Her content connects saving, budgeting, investing, insurance, and debt decisions to real-life goals such as child education, marriage, retirement, home buying, emergency funds, family protection, and long-term wealth building.
She covers topics such as child education planning, marriage goal planning, retirement planning, home-buying goals, inflation-based goal estimation, monthly investment planning, savings timelines, emergency buffers, asset allocation basics, family financial milestones, and goal calculators.
Ishita’s writing is structured, thoughtful, and decision-oriented. She helps readers move from vague goals like “save more” to clearer questions such as how much may be needed, by when, what assumptions matter, and what trade-offs exist. Her articles use Indian examples, timelines, ₹ amounts, and simple planning frameworks. Her content is educational and should not be treated as personalised investment, tax, loan, or insurance advice. Since future costs, inflation, returns, product rules, and tax treatment can change, readers should verify current information before acting.