Insurance

The Insurance category explains important insurance concepts for Indian families, salaried employees, self-employed professionals, and first-time policy buyers. This section can cover term insurance, health insurance, life insurance, riders, claim settlement, waiting periods, exclusions, deductibles, co-payment, no-claim bonus, family floater plans, critical illness cover, employer insurance vs personal insurance, tax benefits, and policy document reading.

Insurance is often misunderstood because many buyers focus only on premium amount, tax saving, or agent recommendations. Ridhi’s insurance guides aim to explain what a policy covers, what it excludes, how claims work, and how readers can compare policies more carefully. This category should help users understand the difference between protection and investment, the importance of adequate coverage, and the risks of buying a policy without reading terms. It is useful for young professionals, parents, families, and people reviewing employer-provided insurance. Insurance premiums, benefits, exclusions, and claim conditions vary by insurer, age, health, and policy wording. Insurance is a subject matter of solicitation, and readers should read the official policy document carefully before purchasing.
family floater health insurance under 20000 india

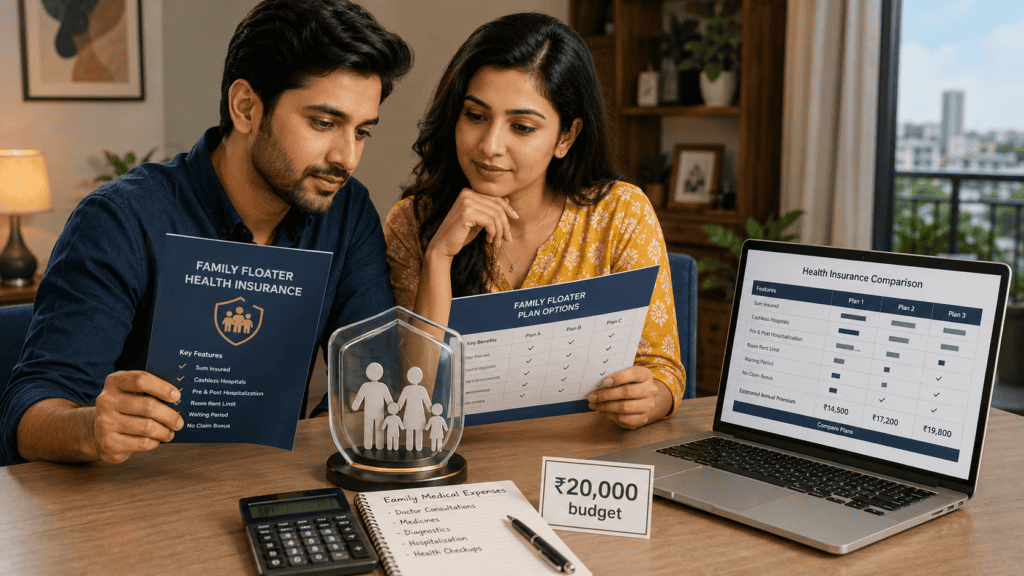
Family Floater Health Insurance Under ₹20,000: What to Check Before Buying

You’ve seen the premium. It fits your budget. But before you buy that family floater health insurance plan under ₹20,000, there’s a harder question to answer: does the policy actually protect your family when a real medical emergency hits? Family floater health insurance under 20000 is not a category of plans — it’s a budget

Family Floater Health Insurance Under ₹20,000: What to Check Before Buying Read More »

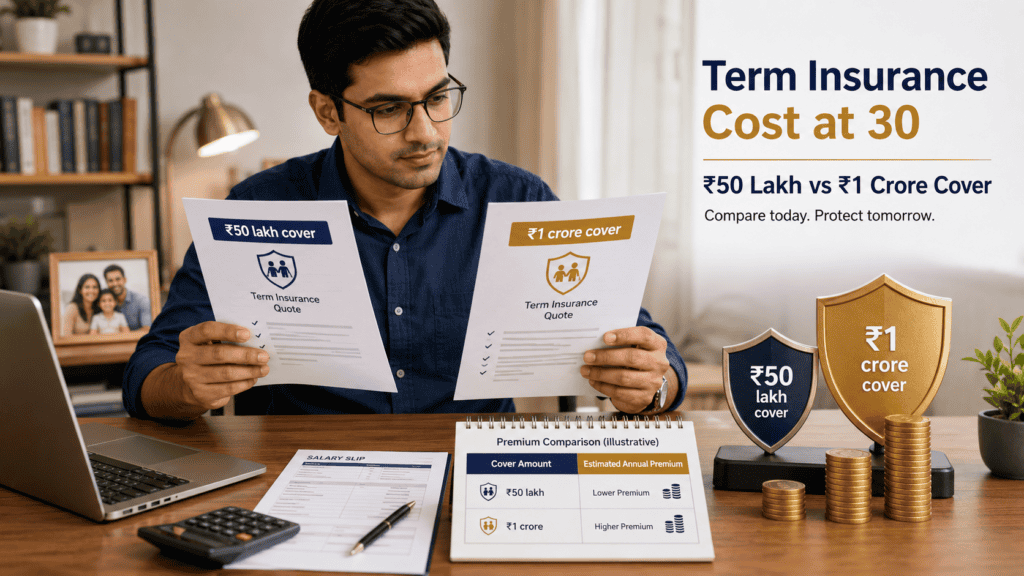
term insurance cost 30 year old 50 lakh vs 1 crore cover

Term Insurance Cost for a 30-Year-Old Salaried Person: ₹50 Lakh vs ₹1 Crore Cover

Most 30-year-olds buying term insurance for the first time face the same question: is ₹50 lakh enough, or should I stretch to ₹1 crore while I am still young and relatively healthy? The answer is not as simple as comparing two annual premium figures. Term insurance cost for 30 year old buyers depends on age,

Term Insurance Cost for a 30-Year-Old Salaried Person: ₹50 Lakh vs ₹1 Crore Cover Read More »

nri family travel insurance india medical coverwebp

Travel Insurance for NRI Family Visiting India: Coverage, Claims and Common Exclusions

Your NRI family has planned a 5-week India trip. Flights are booked, relatives are excited, and itineraries are sorted. What most families skip — until something goes wrong — is checking whether anyone is actually covered if there is a sudden hospitalisation in India. Your overseas health plan may not work in India. The local

Travel Insurance for NRI Family Visiting India: Coverage, Claims and Common Exclusions Read More »

best term insurance for women india

Best Term Insurance for Women: Premium, Coverage and Mistakes to Avoid

Most women searching for term insurance start with one question: which plan has the lowest premium? That is a reasonable starting point — but it is not the right ending point. If you are a salaried woman with a home loan, a child, and parents who depend partly on your income, the cheapest ₹50 lakh

Best Term Insurance for Women: Premium, Coverage and Mistakes to Avoid Read More »

claim settlement ratio insurance india

Claim Settlement Ratio Meaning: How to Use It to Choose an Insurer

You’ve shortlisted two term insurance plans. Both look similar on paper — same cover, similar premium, almost identical features. Then someone tells you: “Check the claim settlement ratio.” One insurer has 98.5%, the other has 96.2%. So the first one is safer, right? Not necessarily. The claim settlement ratio is useful — but most buyers

Claim Settlement Ratio Meaning: How to Use It to Choose an Insurer Read More »

ulip vs term insurance mutual fund comparison

ULIP vs Term + Mutual Fund: Real Comparison with Numbers

Your bank relationship manager, insurance agent, or a colleague at the office has probably pitched this at some point: “Sir, one plan — insurance plus investment. Cover for your family, returns for your future.” It sounds efficient. But when you sit down to compare actual numbers, the picture gets complicated fast. ULIPs — Unit Linked

ULIP vs Term + Mutual Fund: Real Comparison with Numbers Read More »

home insurance in india premium coverage family protection

Home Insurance in India: Premium, Coverage and Who Actually Needs It

Most Indian families insure their cars without a second thought. Many now buy health insurance. Yet the ₹80 lakh flat they spent years saving for — with all its furniture, electronics, and personal belongings — often sits completely uninsured. Home insurance in India remains one of the most under-purchased financial products, even as floods, earthquakes,

Home Insurance in India: Premium, Coverage and Who Actually Needs It Read More »

life insurance maturity proceeds tax rules salaried people

Life Insurance Maturity Proceeds Tax Rules for Salaried People

You received a maturity payout from a life insurance policy — ₹10 lakh, maybe more — and now you are not sure whether it is tax-free, partly taxable, or already settled because TDS was deducted. This confusion is common among salaried people in India, and it costs money when handled incorrectly at ITR time. Life

Life Insurance Maturity Proceeds Tax Rules for Salaried People Read More »

accidental death benefit rider term insurance india

Accidental Death Benefit Rider: Worth Adding to Term Insurance?

You are buying a ₹1 crore term plan online. Everything is filled out. Then a checkbox appears: “Add Accidental Death Benefit Rider — ₹25 lakh cover.” The price looks small. You tick it without reading further. That split-second decision is where most salaried buyers go wrong — not because the rider is necessarily bad, but

Accidental Death Benefit Rider: Worth Adding to Term Insurance? Read More »

car insurance add ons zero depreciation engine protectwebp

Car Insurance Add-Ons Worth Paying: Zero Depreciation vs Engine Protect

Every time you renew car insurance, the insurer or broker asks whether you want zero depreciation, engine protect, consumables cover, roadside assistance, and a handful of other add-ons. Most people either say yes to everything — which inflates the premium — or say no to everything — which can mean a large out-of-pocket bill after

Car Insurance Add-Ons Worth Paying: Zero Depreciation vs Engine Protect Read More »